Edinburgh Itinerary 3 Days: A Practical Plan
Use this Edinburgh itinerary 3 days plan for honest sightseeing, transit tips, free stops, museums, budget notes, and what to skip.
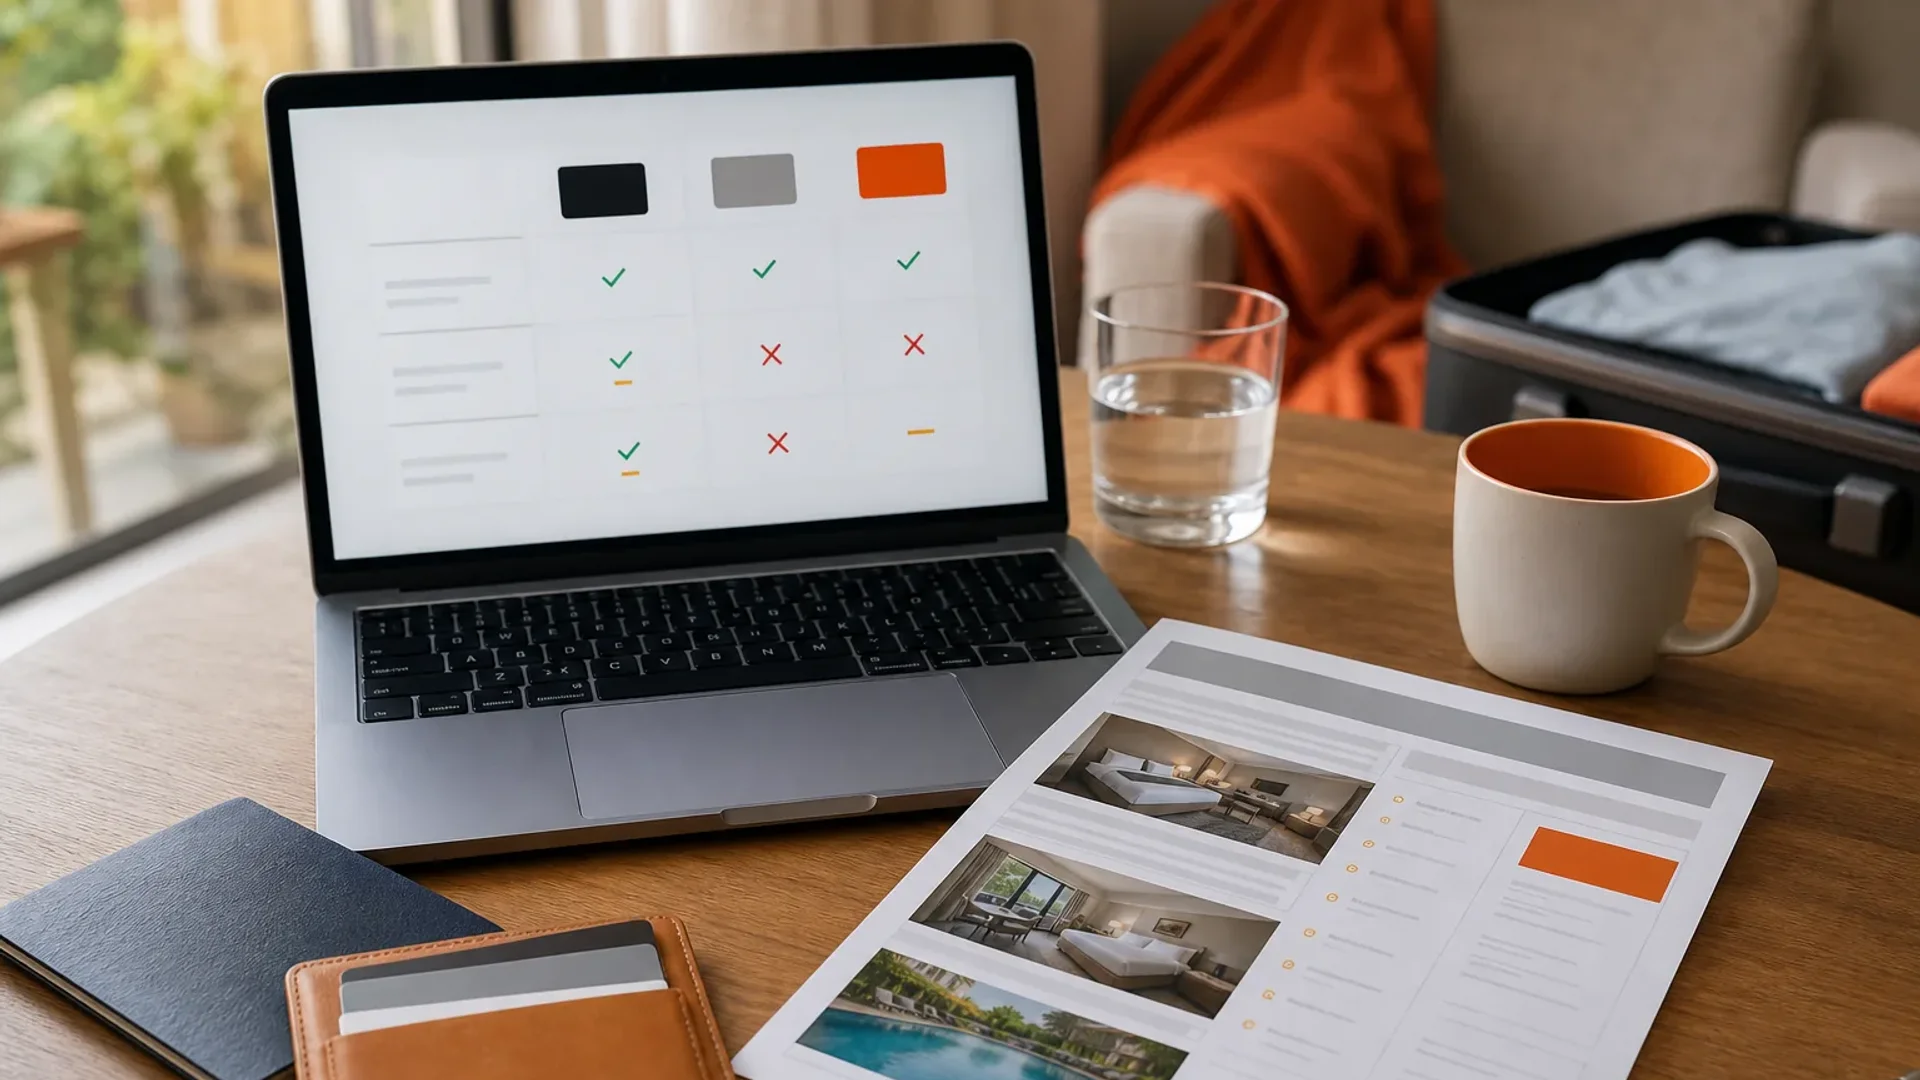
Hotel cards can turn one planned stay into a free night, late checkout, or a better room. But a flashy bonus won’t help if you never use the hotel brand. The comparison covers eight cards and offers a simple way to choose the right fit for your next three stays.
Some links in this article are affiliate links. If you book through them, we earn a small commission at no extra cost to you. We only include affiliate links for things we’d recommend regardless. If we wouldn’t send a friend there, it’s not here.
The best credit cards for hotel points usually fall into three groups: no-fee cards, low-fee cards, and premium cards. Compare the hotel partner first. Then check the earning rate and the benefit you can use each year.
Hilton cards dominate this sample. Four of the eight cards work with Hilton Honors. The no-fee Hilton Honors American Express Card earns 7X per dollar on hotel purchases. That rate beats the 6X listed for the Marriott Bonvoy Business® American Express® Card, even though the Hilton card has no annual fee.
The Hilton Honors American Express Surpass® Card raises the hotel rate to 12X and has a $150 annual fee. The Hilton Honors American Express Business Card also lists 12X, with a $195 annual fee. Those cards make more sense when you expect several Hilton stays and can use the added card benefits.
Marriott gives you a different trade-off. The Marriott Bonvoy Business® American Express® Card has a $125 fee and earns 6X on Marriott hotel purchases. The Marriott Bonvoy Brilliant American Express Card carries a $650 fee. Its listed welcome offer includes 150,000 Marriott Bonvoy points plus a $250 statement credit after the required spend.
That large bonus needs a plan. A bonus is useful when you already know where you can redeem it. It is weak if it pushes you toward a hotel you would not have booked.
Elite status can also change the math. Depending on the card and property, status may help with late checkout, room upgrades, breakfast, or a welcome gift. None of those perks is guaranteed at every hotel. Availability and brand rules still control the stay.
We also keep the weak spots in view. Hilton points tend to need more points for a stay than some other hotel currencies. Marriott breakfast rules can vary by brand. Status may mean a nicer room, but it does not promise a suite.
Make a short list of the hotels you would book with cash. If most belong to one chain, a co-branded card may fit. If the list is mixed, move to flexible rewards.
Flexible travel cards may suit you better when hotel loyalty changes by trip. They earn points through a travel portal or on broad travel spend, then let you choose among redemption paths.
Chase Sapphire Preferred® has a $95 annual fee. The card earns 5X on Chase Travel and 2X on other travel purchases, based on the listed terms. It also has transfer options to frequent travel programs. That makes it useful for someone who stays at different hotel brands and wants a lower yearly cost.
Chase Sapphire Reserve® sits at the premium end with a $795 annual fee. It earns 8X through Chase Travel, 4X on direct hotel bookings, and 3X on dining worldwide. It also lists up to $300 in annual travel statement credits. The card includes access to Chase Sapphire Lounges and eligible airport lounges, subject to its terms.
Those benefits only count when you use them. If you book direct to earn hotel status, a portal bonus may not beat the value of that status. If you rarely visit an airport lounge, lounge access should not carry much weight in your calculation.
The key difference between the two Sapphire cards is that Preferred keeps the fee lower, while Reserve adds more travel credits and premium benefits. Compare the official Chase Sapphire Preferred terms with the Reserve terms before applying.
Pro Tip: Price the same room through the hotel and the travel portal before you decide where to book.
A flexible card wins when choice matters more than hotel status. A co-branded card wins when you return to the same chain often.
The annual fee is only worth paying when you can use the benefits without changing your travel habits. Write down the fee first. Then add only the value you would actually claim.
Use this four-line test:
For example, a $150 fee can be sensible for a Hilton traveler who uses the 12X hotel rate and receives enough value from the card’s other benefits. It may be wasteful for someone who books one Hilton stay every two years.
The same rule applies at the premium end. The Marriott Bonvoy Brilliant American Express Card lists a $650 annual fee, a 150,000-point welcome offer, a $250 statement credit, a yearly free night award capped at 85,000 points, and Platinum Elite status. Those items look strong. They still need to match your stays.
The average annual fee in this eight-card sample is $287, while the median is $150. The gap comes from high-fee cards such as Chase Sapphire Reserve®. Averages can make the market look pricier than the card most readers will actually choose.
Use a use-it-or-lose-it rule when comparing annual fees at Dream Book Travel. Do not assign full value to a perk you would forget, skip, or pay extra to use.
Card fees and benefit details can change. Check the Marriott Bonvoy card information before you apply, since offers and terms can change.
Point value depends on the booking, not the balance on your screen. A large number can still buy a poor room if the award price is high.
Start with a cash comparison. Find the room’s cash rate, then divide that rate by the points needed. If a room costs $200 or 40,000 points, the redemption gives you half a cent per point. Include taxes, resort fees, and any cash charge that remains.
Hotel currencies do not behave alike. Marriott points sit near seven-tenths of a cent in the cited video research. Hilton points are often less valuable than other hotel currencies, so a high earn rate does not automatically mean high value.
Compare redemption value beside the earning rate. A 12X card can earn points fast, yet those points may need a large balance for one night. A lower multiplier can win if the award chart or cash rate gives you more value per point.
Check the same room on three dates. A weekday award may make sense while a weekend award does not. Then ask if you would pay the cash price. If the answer is no, do not count the full cash rate as savings.
Key Takeaway: Choose the card that helps you earn points you can redeem well, not the card with the biggest multiplier alone.
A sign-up bonus can provide the fastest first-year value, but only if you can meet the spending requirement with planned purchases. Never buy extra goods to chase points.
In the sample, welcome bonuses average 105,714 points. The Marriott Bonvoy Brilliant offer of 150,000 points pulls that average upward. The size of a bonus often reflects the hotel’s effort to attract new members, not the long-term value of the card.
Before applying, compare the public offer with any offer in your bank account. Targeted offers may arrive by email, mail, or inside an account dashboard. CardMatch can show improved offers after a soft credit check, though an actual application creates a hard inquiry and approval is never certain.
Portal price matters too. Some travel rewards cards list 5X miles on hotels booked through their travel portals. They may also list a price match guarantee for flights, hotels, and rental cars, subject to the portal’s terms. Read the process before booking. A lower portal price only helps if the booking qualifies and you can complete the match request correctly.
The card’s details also list 2X miles on every purchase, a $95 fee, and a credit toward Global Entry or TSA PreCheck. Those features may matter more than hotel status for someone who changes brands often.
Set a price alert before you commit. Then save a screenshot of the public offer and your targeted offer. It takes a few minutes and can prevent a costly mistake.
The right card is the one that fits your next three stays and your normal spending. If the card requires a new travel habit, its value is probably overstated.
Use this decision rule:
Skip any card that encourages you to spend more than planned. Also skip a premium card if you cannot explain where its credits will go. A free breakfast sounds useful until the property does not provide it for your rate or brand.
Check eligibility before submitting an application. Issuers may limit welcome bonuses based on prior card ownership, past bonuses, account history, or credit profile. The public offer page is the final word on the terms.
For readers who travel for work, our comparison of business credit cards for travel may help separate business spending from personal hotel plans. Keep that choice tied to actual business purchases.
We recommend making the decision on a blank sheet. List the hotel, cash rate, award rate, fee, and benefit you will use. The guides won’t know your travel window, but you do.
The Hilton Honors American Express Card is the clearest no-fee option in this sample because it lists 7X points per dollar on Hilton hotel purchases. It may suit someone who wants to try Hilton without paying a yearly fee. The trade-off is fewer premium benefits, so compare the value of status and credits before applying.
Hotel credit cards are worth the annual fee when you can use their free night, status, credits, or higher earning rate during the year. A $150 fee may work for a regular Hilton guest, while a premium fee needs much more use. Price your likely stays first. Do not count perks you would not claim.
Choose a hotel card when you return to one chain and want its points or status. Choose a flexible travel card when your hotel brand changes by trip. Chase Sapphire Preferred® earns through Chase Travel and other travel categories, while co-branded cards focus on one hotel program. Your booking habits should decide.
You get more value from hotel points by comparing the cash rate with the award rate before booking. Test several dates and include fees that remain payable in cash. Use the card at its partner hotel when the earning rate fits your plan. A large points balance is less useful when the redemption gives poor value.
Yes, you can check for a higher welcome bonus through targeted offers, bank account dashboards, referral links, or CardMatch. Offers can change and may not be available to everyone. A soft check through CardMatch does not affect your credit score, but applying for a card creates a hard inquiry. Always read the spending terms.
We would start with the no-fee Hilton card if Hilton is already on your route and you want a low-risk test. Pick a paid card only when its fee matches stays you have already planned. Before you apply, write down the next three hotels, compare direct and portal prices, and check the current offer. Dream Book Travel can help you make that choice without turning every trip into a points puzzle.
Use this Edinburgh itinerary 3 days plan for honest sightseeing, transit tips, free stops, museums, budget notes, and what to skip.
Find the best areas to stay in London for tourists, with honest advice for first-time visitors, culture lovers, foodies, and theater fans.
Find the best Greek islands for families by travel style, beach access, activities, and travel-day tradeoffs. Honest picks and planning notes.